Menu
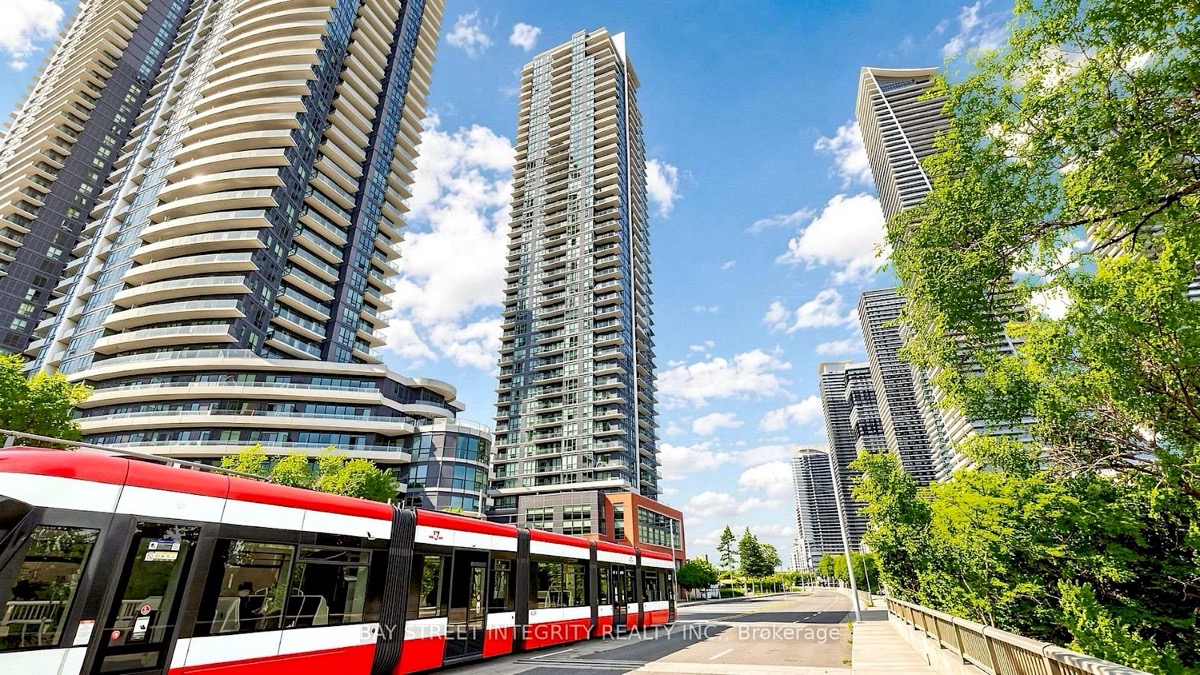
Westlake Village · Renter to buyer decision
Rent or buy the condo? The monthly payment is not the full answer.
Explore a historical $2,350 Westlake one-bedroom lease against a $465,000 resale example—with costs, equity and uncertainty kept separate.
Verified REALM historyInteractive monthly budgetNo guaranteed winner
Compare your own numbers ↓A decision real renters face
What if you rented in Westlake—and now want to own?
Imagine a household enjoying the Westlake towers at 2200, 2212 or 2220 Lake Shore Blvd West. Paying rent every month can feel like missing out on ownership. But buying the next available suite may require a large down payment, closing costs, higher monthly cash flow and accepting responsibility for the building's future repairs.
It is equally possible to regret waiting too long if a home genuinely suits your household and your financial plan. The answer depends on your time horizon, exact unit, financing and tolerance for uncertainty—not a generic social media claim that rent is wasted money or homeownership always wins.
Historical completed Westlake transactions · not current listings
Start with evidence, not a guessed market price.
These archived REALM/PropTx groups cover September 20, 2025 through September 19, 2026 in the three Westlake addresses only. The sale and lease samples are not the same units. The $616 fee is an all-sale median, not a one-bedroom match. None of these numbers is an October 2026 active listing quote or an appraisal. View the underlying Westlake building guide for more historical product detail.
Change the assumptions yourself
Cash flow and economic cost are not the same.
Under the starting illustration, ownership requires a down payment and closing cash while the mortgage payment includes both interest and principal. Compare the monthly cash amounts first; then ask which part changes your net wealth and which risks remain.
Adjustable · illustrative only
Compare your own monthly cash flow
Start with dated Westlake sale and lease medians, then replace them with exact listing details. The rate and non-MLS costs are hypothetical, not a lender quote. We use the Canadian-style nominal fixed rate compounded semiannually for a simplified payment estimate.
Renting
Buying
Owning minus renting · monthly cash+$630This is a cash-flow comparison, not a prediction of which option builds more wealth.
Inside the first mortgage payment
Estimated monthly mortgage payment$2,059
First month interest component$1,382
First month principal paid down$677
Owner cash excluding first-month principal$2,328
Principal repayment reduces debt; it is not a tax or service expense. But it also cannot be used to pay your monthly bills, and equity remains exposed to resale prices and transaction costs.
Cash needed before buying
Down payment$93,000
Ontario + Toronto transfer taxes after assumed rebates$11,550
Est. 8% Ontario insurance premium tax (if insured)$0
Illustrative legal / title + adjustments$3,000
Illustrative upfront cash$107,550
Assumes $2,000 legal/title and $1,000 adjustments; excludes other expenses and may be higher. If down payment is less than 20%, an estimated insured mortgage premium of $0 is added to mortgage principal in this model. Confirm actual insurance, lender and closing terms.
No mortgage approval or five-year financial forecast is implied. This calculator deliberately does not project price appreciation, rent inflation, investment returns, tax benefits, future special assessments or selling commissions. Such factors can change the economic outcome substantially. All figures are CAD, and entries stay in this browser session.
Three layers of the decision
Do not let one monthly number make the decision for you.
Cash flow
Rent, insurance and your own utilities versus mortgage payment, condo fee, tax, insurance, utilities and an owner repair allowance. Both sides must be affordable using the actual lease and status certificate.
Equity and opportunity cost
Mortgage principal reduces debt, but a down payment ties up cash that could otherwise remain liquid or invested. Capital values can rise or fall, and transaction costs are real. We do not forecast a guaranteed investment return.
Time and risk
Buying adds legal fees, taxes, future sales costs, condo corporation obligations and possible special assessments. Renting may preserve mobility, though lease terms and future rents also matter.
Four questions before choosing
When renting makes sense—and when buying might.
Would you stay long enough for ownership to fit?
If you expect to move soon, closing expenses and future selling costs may outweigh some benefits of a stable housing plan. There is no magic universal break-even year, and resale prices can move either way.
Can you fund the upfront cash without exhausting reserves?
A 20% down payment is not the entire closing bill. Include both Ontario and Toronto transfer taxes, lawyer, adjustments, insurance taxes when relevant and a separate emergency reserve after receiving the keys.
Have you checked the exact condo corporation?
A current status certificate, budget, reserve study, unit fees and possible assessments may reveal ownership obligations not reflected in the price. A median fee from an older dataset is not due diligence.
How valuable is flexibility to your family?
Renting may make a job change or relocation easier; owning may give more control subject to governing documents and a mortgage. Neither wins for every household.
The fairest comparison is unit-by-unit. Replace these historical medians with the available suite's current lease or offer price, actual square footage, condominium fee, included utilities, property tax, insurance and status certificate. Then compare your likely length of stay and emergency reserves with a lender and lawyer. Renting is not automatically throwing money away; buying is not a guaranteed investment gain.
Sources and related decisions
Verify every assumption before committing.
Financial Consumer Agency of Canada · Buying a home ↗FCAC · Independent mortgage calculator ↗CAO · What condo common expenses cover ↗CAO · Read your exact unit status certificate ↗Toronto closing cash guide →Renter budgeting and application guide →Seven buyer certificate checks →
The historical source periods end September 19, 2026. All mortgage-rate and ancillary expense amounts are illustrative assumptions only. Additional possible costs include financing charges, closing administration, property taxes, condo special assessments, a sale later on, and the opportunity cost of committed funds. The model excludes all home appreciation and rent inflation forecasts.
Frequently asked renter-to-owner questions
Before you trade rent for a mortgage
Is it cheaper to rent or buy a one-bedroom Westlake condo in 2026?
There is no defensible universal winner. Archived Westlake records contain 17 one-bedroom condo sales with a $465,000 median and 61 one-bedroom condo leases with a $2,350 monthly median over September 2025–September 2026. They are different homes and are not a current October price quote. Your real cash flow and the longer-term economic outcome depend on actual units, financing, holding period and costs.
Does a mortgage payment count entirely as an ownership cost?
No. Every normal amortizing mortgage payment includes an interest part and a principal repayment part. Principal reduces outstanding debt and can build equity, but owners must still have enough cash each month, and equity may rise or fall with property value and selling expenses. Compare cash flow separately from economic costs.
Why did you use a $616 Westlake condo fee?
The $616 figure is a historical all-unit median common-expense amount among 36 Westlake closed condo sales, not a matched one-bedroom fee. Actual fees depend on the exact suite, corporation and included services. Obtain current status certificate records, utility allocations, property taxes and future repair information.
What is the cash required to buy a $465,000 condo?
At an illustrative 20% down payment ($93,000), transfer taxes on a Toronto property are $5,775 provincially and $5,775 municipally before eligible first-time relief. With assumed $2,000 legal/title and $1,000 adjustments, the simplified no-rebate total is $107,550. Fully eligible first-time relief would reduce that to $99,075. Other costs and actual lawyer/lender amounts still apply.
How do I compare rent versus owning if I expect to move in two years?
Shorter ownership periods can make closing taxes, legal fees, selling expenses and price volatility especially relevant. Avoid treating a short holding period or projected price gain as certain. If timing and job location are unsettled, renting may provide useful flexibility. Calculate unit-specific costs and ask your lender, lawyer and other professionals before deciding.
What if I have less than a 20% down payment?
You may need an insured mortgage, subject to lender and insurer rules. The calculator estimates a standard mortgage insurance premium, adds it to mortgage principal, and separately shows the Ontario 8% tax on the premium as an upfront cash amount. Eligibility and premium may differ for certain down-payment sources or mortgage types.
Does a first-time buyer automatically qualify for both land transfer tax rebates?
No. Ontario and City of Toronto each have program requirements; factors such as ownership of a home anywhere in the world, spouse history, citizenship/permanent residency and principal residence use can affect eligibility. The calculator assumes no rebates unless explicitly selected, and your lawyer must verify any actual claim.
Decide with the exact home in mind
Compare the available rental with the condo you would actually buy.
Tell me your budget, whether you are renting or hoping to buy, how long you expect to stay and which Westlake tower or Humber Bay Shores streets you prefer. I can help you find real unit-level comparisons rather than reuse an outdated median.